
Written by Ilham Indra, Marketing Communication at PT Korea Investment Management Indonesia. Reviewed by Compliance before publication.
Almost every explanation of mutual funds online is written by someone selling or reviewing the product. This article is written from a different position: the party that manages the money every day.
That difference matters, because what confuses beginners most is rarely the definition. It is who holds what, and who is responsible for what.
What a Mutual Fund Is
A mutual fund is a vehicle that pools money from many investors to be invested in a portfolio of securities by an investment manager licensed by the Financial Services Authority. Investors receive Participation Units as proof of ownership, and their value follows the portfolio's net asset value.
Three words carry the meaning: pooled, managed, supervised. Money from many people is combined, managed by a licensed party, and the whole process sits under regulatory supervision.
How Is Your Money Managed?
The investment manager's role
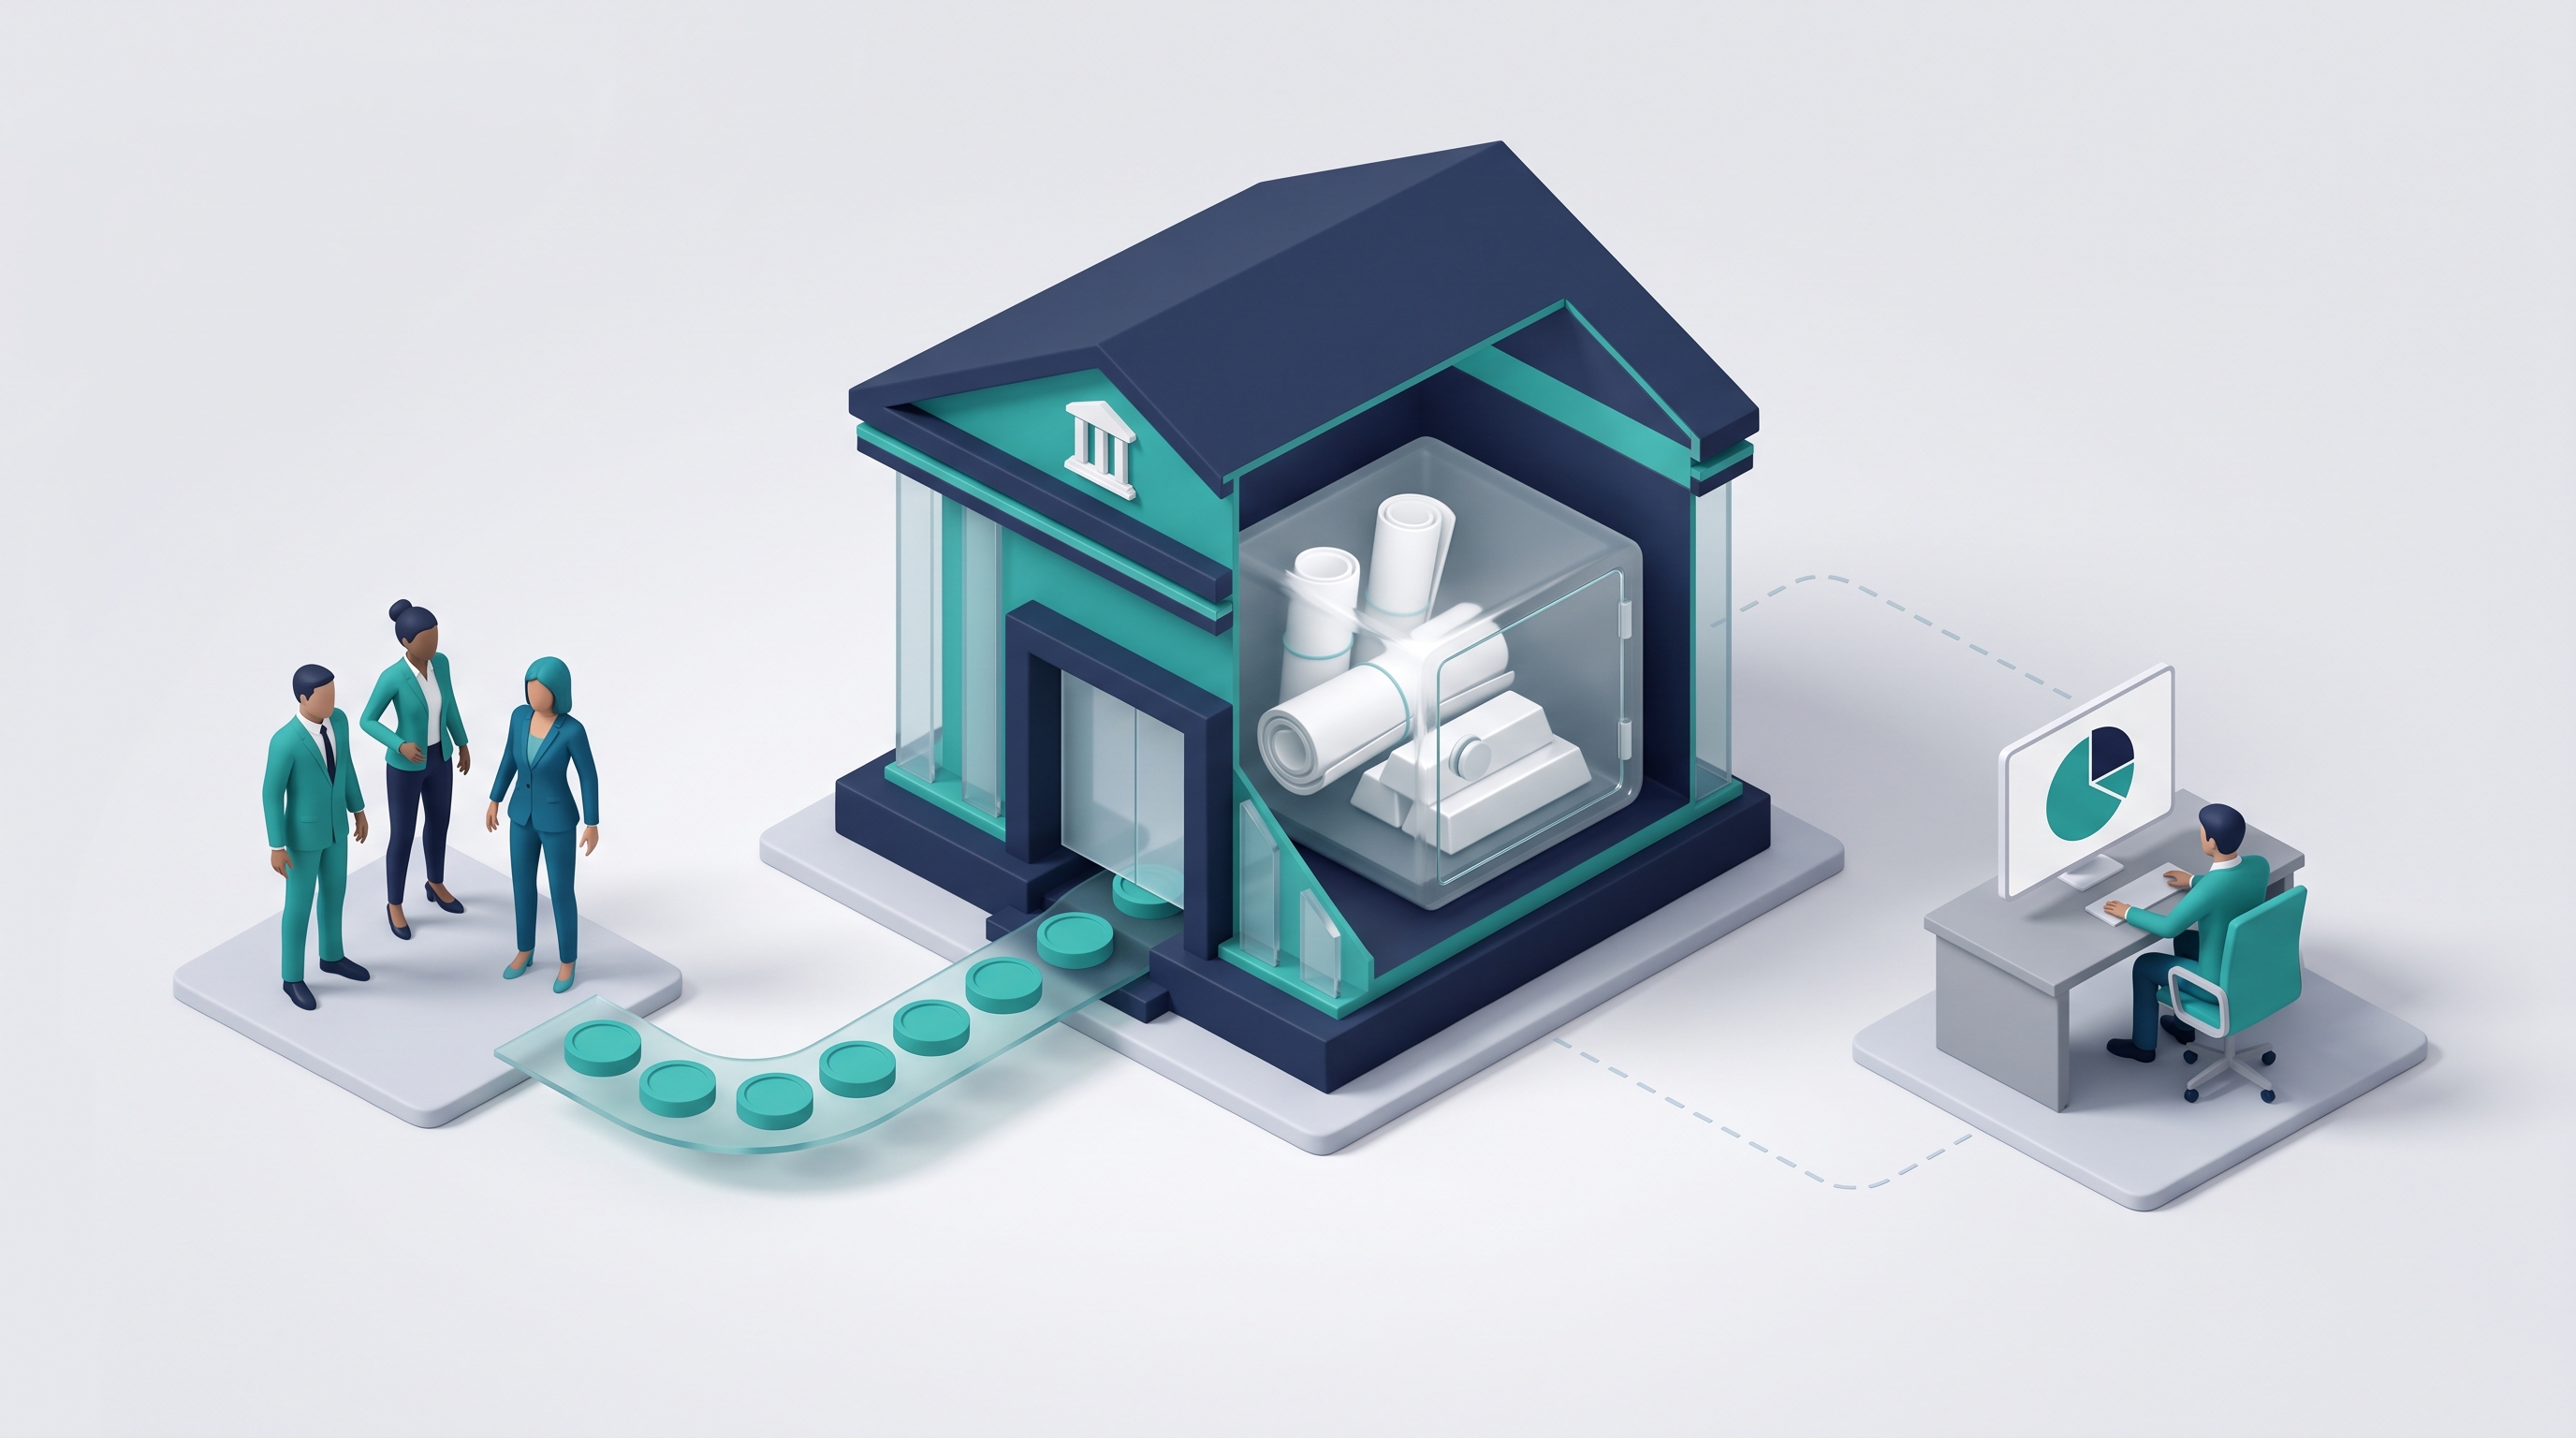
The investment manager decides which securities to buy and sell, when, and in what proportion, in line with the investment policy written in the prospectus. The investment manager does NOT hold investors' money.
The custodian bank's role
The custodian bank holds investors' cash and securities, records ownership of Participation Units, and calculates the net asset value on every trading day. This separation is the most fundamental protection in the mutual fund structure.
Because assets sit with a separate custodian bank, investors' assets are not mixed with the investment manager's own. This answers the question that comes up most often: where is the money actually kept.
How money flows in and out
The investor transfers money to the custodian bank's account, not to the investment manager's account.
The custodian bank records the number of Participation Units acquired based on that day's net asset value per unit.
The investment manager manages the portfolio according to the investment policy in the prospectus.
When the investor sells back, the custodian bank pays out according to the prevailing net asset value per unit, less applicable fees.
What Types of Mutual Fund Are There?
Types are distinguished by what sits in the portfolio, and that composition determines both the risk profile and the horizon that suits it.
Type | Portfolio contents | Typical horizon |
|---|---|---|
| Money market | Instruments maturing under one year and deposits | Under 1 year |
| Fixed income | Predominantly debt securities | 1-3 years |
| Balanced | A mix of debt securities and shares | 3-5 years |
| Equity | Predominantly shares | Over 5 years |
| Index | Tracks the composition of a reference index | Follows the index's asset class |
A full explanation of each type and how to match it to a goal is available in our article on types of mutual funds.
Terms to Understand First
- Net asset value: the fair value of all the fund's assets less its liabilities. Covered in our article on net asset value.
- Participation Unit: the unit of an investor's ownership in the fund.
- Prospectus: the official document setting out the investment objective, investment policy, costs and risk factors.
Custodian bank: the party that holds the assets and calculates net asset value.
What Are the Benefits and Risks?
Both come from the same source and need to be read as a pair.
Benefit | The risk that comes with it |
|---|---|
| Managed by a licensed party, so the investor need not pick securities. | Investment decisions rest with the investment manager, not the investor. |
| Automatic diversification, since money is spread across many securities. | Diversification reduces risk but does not remove it. |
| The investment can grow in line with portfolio performance. | It can also fall, including below the initial subscription value. |
| Redemption is generally available on any trading day. | Payment timing follows the prospectus and is not always immediate. |
Past performance does not guarantee future performance.
How Does It Differ from a Deposit or Shares?
The most important difference is insurance. Bank deposits are covered by the Deposit Insurance Corporation up to certain limits and conditions. Mutual funds are NOT covered by deposit insurance.
Compared with buying shares directly, a mutual fund moves the security selection to the investment manager and spreads money across many holdings at once. In exchange there are management costs, and the investor does not choose the individual securities.
About the Manager
PT Korea Investment Management Indonesia is an investment manager registered with and supervised by the Financial Services Authority under licence number KEP-50/D.04/2019, operating in Indonesia since 2019.
Frequently Asked Questions
Are mutual funds covered by deposit insurance?
No. Mutual funds are not covered by the Deposit Insurance Corporation. That guarantee applies to bank deposits, not to investment products.
Can you lose money in a mutual fund?
Yes. The value can fall, including below the initial subscription value. Past performance does not guarantee future performance.
Who actually holds my money?
The custodian bank. The investment manager makes investment decisions but does not hold investors' money, and investors' assets are kept separate from the manager's own.
What is the minimum purchase?
It is set by each investment manager and stated in each product's prospectus. The amount differs between products.
Are mutual funds supervised by the Financial Services Authority?
Yes. Investment managers must be licensed and supervised, and every fund must receive an effective statement before being offered.
How does a mutual fund differ from a time deposit?
A deposit pays interest fixed in advance and is insured up to a limit. A mutual fund pays no fixed interest, its value fluctuates, and it is not covered by deposit insurance.
Next Steps
- Learn the types of mutual fund and how to match one to your goal.
- See the range of funds managed by PT Korea Investment Management Indonesia on the Products page.